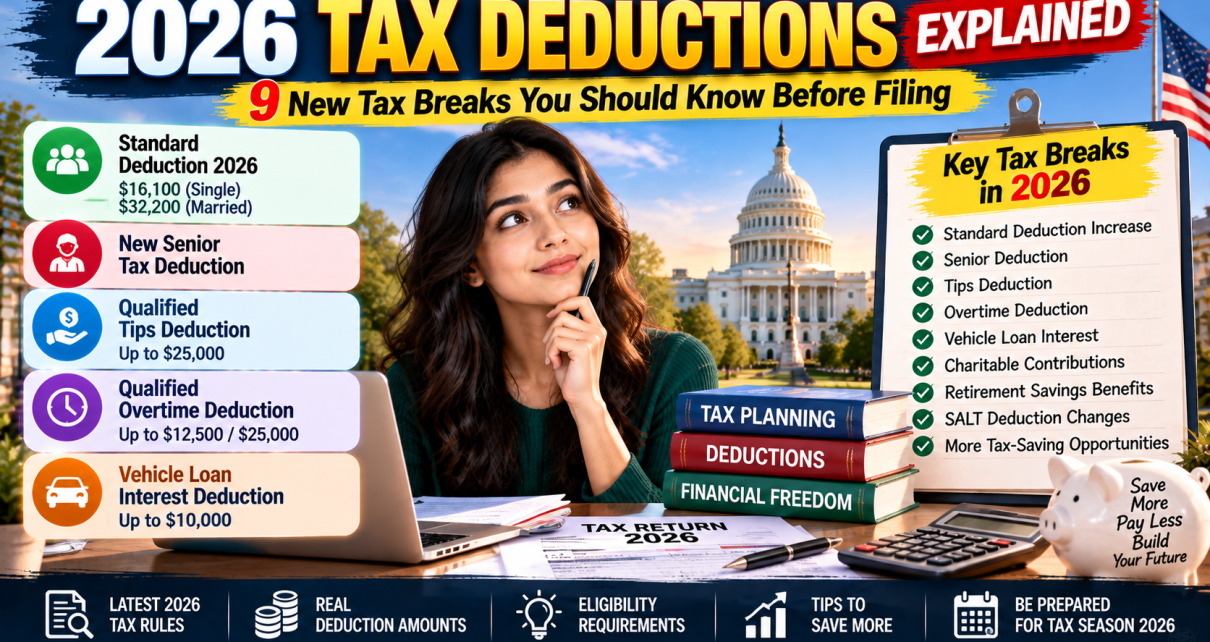
2026 Tax Deductions Explained: 9 New Tax Breaks You Should Know Before Filing
Tax rules are changing, and 2026 includes several deductions and tax provisions that could affect how much taxable income you report and how much federal income tax you ultimately owe.
But there is an important point to understand before looking at the numbers.
Tax year 2026 generally means income you earn during calendar year 2026, with the corresponding federal income tax return generally filed in 2027. Some of the deductions discussed in this article, however, were introduced beginning with tax year 2025 and also apply during 2026.
That distinction matters because “2026 tax changes” can refer either to changes affecting returns filed during 2026 or changes affecting income earned during 2026.
This guide focuses primarily on tax year 2026 and highlights nine important deductions and tax breaks that taxpayers should understand before filing.
Some of these provisions are genuinely new. Others are updated amounts or expanded deductions that can be especially important in 2026.
The rules also vary by income, filing status, age, type of income, and whether you itemize deductions.
Here are nine important 2026 tax deductions and tax breaks to know.
- The Higher 2026 Standard Deduction
The standard deduction remains one of the most important tax breaks for individual taxpayers.
Instead of listing eligible expenses one by one on Schedule A, taxpayers who qualify can generally use the standard deduction to reduce the amount of income subject to federal income tax.
For tax year 2026, the standard deduction is:
Single: $16,100
Married filing jointly: $32,200
Head of household: $24,150
Married filing separately: $16,100
These amounts are higher than the corresponding 2025 amounts because of the annual tax-law adjustments.
The standard deduction is particularly important because many taxpayers do not itemize.
For example, suppose a married couple filing jointly has $150,000 of income and takes the $32,200 standard deduction.
The simplified calculation would be:
$150,000 − $32,200 = $117,800
That $117,800 is not necessarily the couple’s final tax bill or even the exact amount used for every tax calculation. Other deductions, adjustments, credits, and forms of income can affect the final return.
It also does not mean all $117,800 is taxed at one rate.
Federal income tax uses marginal brackets, so different portions of taxable income are taxed at different rates.
The key takeaway is that the standard deduction directly reduces taxable income and can be more valuable than itemizing for many households.
The IRS confirms the 2026 standard deduction amounts and the 2026 tax-bracket adjustments.
- The New $6,000 Senior Deduction
Taxpayers age 65 and older may have another significant deduction available in 2026.
A new enhanced senior deduction allows eligible individuals age 65 or older to claim an additional deduction of up to $6,000.
If both spouses qualify and file jointly, the household could potentially receive an additional $12,000 deduction.
This deduction is separate from the additional standard deduction that already exists for taxpayers who are age 65 or older.
That distinction is important.
A qualifying senior may therefore have:
The regular standard deduction
The existing additional standard deduction for being 65 or older
The new enhanced senior deduction
The enhanced senior deduction is subject to an income-based phaseout.
For 2026, the IRS states that the deduction begins to phase out when modified adjusted gross income exceeds:
$75,000 for single filers
$150,000 for married couples filing jointly
The provision currently applies for tax years 2025 through 2028.
For example, imagine a married couple where both spouses are at least 65 years old and their income is below the applicable phaseout threshold.
They could potentially receive:
$32,200 standard deduction
Additional age-based standard deduction
Up to $12,000 enhanced senior deduction
The exact amount depends on the taxpayers’ circumstances and filing status.
Seniors should also pay attention to whether they are using the standard deduction or itemizing because the enhanced senior deduction is available to eligible taxpayers regardless of whether they itemize.
The IRS confirms that the $6,000 senior deduction is available for tax years 2025 through 2028 and can reach $12,000 for a qualifying married couple filing jointly.
- The Qualified Tips Deduction
Workers who receive tips may qualify for a new deduction related to qualified tip income.
The deduction can be worth up to $25,000 per year, subject to the applicable eligibility rules and income phaseouts.
However, “no tax on tips” does not mean every dollar described as a tip automatically becomes tax-free.
The IRS uses a specific definition of qualified tips.
The deduction generally applies to voluntary cash or charged tips received by workers in occupations that customarily and regularly receive tips.
Examples can include certain restaurant workers, bartenders, salon workers, personal trainers, and other qualifying occupations.
The deduction is also subject to an income phaseout.
For 2026, the IRS states that the deduction begins to phase out above modified adjusted gross income of:
$150,000 for individual filers
$300,000 for married couples filing jointly
The maximum deduction is $25,000 per return.
Taxpayers receiving tips should keep accurate records and review their wage statements and other reporting documents.
Self-employed individuals can also have additional limitations because the deduction generally cannot exceed the relevant net income from the business in which the tips were earned.
Another important point is that the tip deduction can be claimed whether the taxpayer itemizes deductions or uses the standard deduction.
The IRS provides specific instructions for determining which tips qualify.
- The Qualified Overtime Deduction
Another major new deduction applies to certain qualified overtime compensation.
Eligible taxpayers may deduct up to:
$12,500 for individuals
$25,000 for married couples filing jointly
The deduction is not necessarily equal to all overtime wages.
The law focuses on qualified overtime compensation that represents the additional amount paid above an employee’s regular rate under the applicable Fair Labor Standards Act requirements.
For example, if an employee normally earns $20 per hour and receives time-and-a-half overtime pay of $30 per hour, the qualified overtime portion can generally relate to the additional $10 per hour rather than the entire $30.
The exact amount must be determined under the applicable rules and reporting requirements.
The deduction begins to phase out for taxpayers with modified adjusted gross income above:
$150,000 for individuals
$300,000 for married couples filing jointly
The deduction can be claimed by eligible taxpayers whether they itemize or take the standard deduction.
Workers should keep their pay stubs, W-2 forms, 1099 forms, and other compensation records.
Do not assume that every payment described by an employer as overtime automatically qualifies.
The IRS specifically defines qualified overtime for this deduction and has issued detailed guidance on how it is calculated.
- The New Car Loan Interest Deduction
One important 2026 deduction missing from many older tax articles is the deduction for qualified passenger vehicle loan interest.
Eligible taxpayers may deduct up to $10,000 of interest paid on a qualifying vehicle loan.
This is not a deduction for the entire car payment.
It applies to qualifying interest.
There are also specific requirements for the vehicle and the loan.
The IRS states that the deduction applies to interest paid on a loan used to purchase a qualified vehicle for personal use, subject to the law’s requirements.
The vehicle must meet specific criteria, including being a qualifying new vehicle.
Lease payments do not qualify for this deduction.
The deduction is also subject to an income phaseout.
For 2026, the phaseout begins when modified adjusted gross income exceeds:
$100,000 for individual filers
$200,000 for married couples filing jointly
The maximum deduction is $10,000 per year.
This provision can be particularly relevant for taxpayers who financed a qualifying new vehicle during the applicable period.
However, do not assume that simply having an auto loan creates a deduction.
The loan, vehicle, purchase date, personal-use requirement, and taxpayer’s income all matter.
Keep the loan agreement, interest statements, purchase documentation, and other records needed to establish eligibility.
The IRS identifies the car-loan-interest deduction as one of the major new individual deductions under the 2025 legislation.
- The Higher SALT Deduction Limit
Taxpayers who itemize deductions may benefit from a significantly higher state and local tax, commonly called SALT, deduction limit in 2026.
For tax year 2026, the overall SALT deduction limit is:
$40,400 for most taxpayers
$20,200 for married taxpayers filing separately
This can include qualifying state and local income, sales, and property taxes, subject to the applicable rules.
The higher limit is especially relevant to taxpayers who live in states or localities with relatively high state and local taxes.
However, the full $40,400 limit is not available to everyone.
The IRS states that the limitation begins to phase down when modified adjusted gross income exceeds:
$505,000 for most filers
$252,500 for married taxpayers filing separately
The limitation cannot reduce the deduction below:
$10,000 for most filers
$5,000 for married taxpayers filing separately
This makes SALT more complicated than simply saying that everyone can deduct $40,400.
For example, a taxpayer with qualifying state and local taxes of $20,000 may potentially deduct the full $20,000 if other requirements are met.
A taxpayer with $60,000 of qualifying SALT expenses may face the statutory limit and, depending on income, potentially a further reduction.
Because SALT is an itemized deduction, taxpayers also need to compare their total itemized deductions with the standard deduction before deciding whether itemizing makes sense.
The IRS has specifically corrected its 2026 guidance to reflect the $40,400 SALT limit and the $505,000 phaseout threshold.
- A New Charitable Deduction for Taxpayers Who Do Not Itemize
Beginning with tax year 2026, taxpayers who take the standard deduction can receive a federal deduction for certain cash charitable contributions.
This is an important change because taxpayers who use the standard deduction generally could not previously claim a separate federal deduction for charitable contributions.
For 2026, eligible non-itemizers may deduct:
Up to $1,000 for individuals
Up to $2,000 for married couples filing jointly
The deduction is limited to qualifying cash contributions made to eligible charitable organizations.
Not every transfer qualifies.
For example, donations to individuals are not deductible charitable contributions.
Certain contributions, such as those involving donor-advised funds and supporting organizations, are also excluded from this new non-itemizer deduction.
Noncash donations such as clothing, stock, or property do not qualify for this particular deduction.
This makes documentation important.
Keep receipts, acknowledgments, bank records, and other evidence showing the amount and recipient of qualifying charitable contributions.
There is another change for taxpayers who itemize.
Beginning in 2026, itemized charitable deductions are generally subject to a 0.5% of AGI floor.
In simple terms, the first 0.5% of AGI in charitable contributions generally does not produce an itemized deduction under the new floor.
For example, if a taxpayer has AGI of $100,000, 0.5% equals $500.
If the taxpayer makes $2,000 of qualifying charitable contributions, the amount potentially deductible under the new floor would generally be $1,500 before other applicable limitations.
These rules make it important to distinguish between itemizers and non-itemizers.
The IRS confirms both the new $1,000/$2,000 non-itemizer deduction and the 0.5% AGI floor for itemized charitable deductions beginning in 2026.
- The Qualified Business Income Deduction Becomes Permanent
Small-business owners and self-employed taxpayers should pay attention to the Qualified Business Income deduction, often called the QBI deduction or Section 199A deduction.
The deduction can allow eligible taxpayers to deduct up to 20% of qualified business income from qualifying businesses.
It can apply to income from certain:
Sole proprietorships
Partnerships
S corporations
Certain trusts and estates
The deduction is not simply a 20% reduction of every dollar a business owner earns.
There are eligibility rules, taxable-income limitations, and additional restrictions that can apply depending on the taxpayer and the type of business.
For 2026, recent legislation also made the QBI deduction permanent rather than allowing it to expire under the previous schedule.
Another change beginning in 2026 is a minimum deduction for certain taxpayers with at least $1,000 of qualified business income from an active trade or business.
The minimum QBI deduction can be $400 for qualifying taxpayers, subject to the applicable rules.
The income thresholds and phase-in ranges also change for 2026.
Because the QBI calculation can become complicated, business owners should not simply multiply their business revenue by 20%.
Qualified business income is generally based on the net amount of qualifying income, gain, deduction, and loss from an eligible trade or business.
Certain types of income do not qualify.
The IRS confirms that the QBI deduction was made permanent and that the 2026 rules include a new minimum deduction for certain active businesses.
- Expanded Casualty Loss Protection for State-Declared Disasters
A less widely discussed 2026 change involves personal casualty losses.
Beginning with tax year 2026, qualifying personal casualty losses associated with state-declared disasters can become deductible in addition to losses associated with federally declared disasters, subject to the applicable requirements.
This is a meaningful expansion of the rules.
For example, suppose a taxpayer’s home or personal property suffers qualifying damage during a disaster that is formally declared by a state.
Under the new 2026 rules, that type of loss may qualify for the federal casualty-loss deduction if all requirements are satisfied.
However, this is not a blanket deduction for every type of property damage.
The rules can involve:
The type of disaster
The declaration status
Insurance reimbursement
The amount of the loss
The property’s adjusted basis
The taxpayer’s AGI
The $100-per-casualty limitation
The 10%-of-AGI limitation
Other applicable restrictions
Taxpayers generally need to reduce a loss by insurance or other reimbursements.
Documentation is also extremely important.
If your property is damaged during a qualifying disaster, keep photographs, repair estimates, insurance records, receipts, and other documentation showing the amount and nature of the loss.
The IRS confirms that beginning in 2026, qualifying personal casualty losses can include losses attributable to state-declared disasters.
2026 Tax Deductions: Which Ones Are Actually New?
One reason tax articles can be confusing is that not every 2026 tax break is technically a brand-new deduction.
Some are new deductions created by recent legislation.
Others are higher inflation-adjusted amounts.
Others are existing provisions that have been expanded or made permanent.
For example:
The $6,000 enhanced senior deduction is new.
The qualified tips deduction is new.
The qualified overtime deduction is new.
The qualified car-loan-interest deduction is new.
The non-itemizer charitable deduction is new for 2026.
The state-disaster casualty-loss expansion is new for 2026.
The QBI deduction becoming permanent is an important legislative change.
The SALT deduction limit has been increased.
The standard deduction has been adjusted upward for inflation.
This distinction is important because it prevents taxpayers from assuming that every provision listed in an online “new tax deductions” article was created from scratch for 2026.
Understanding Tax Deductions vs. Tax Credits
A tax deduction and a tax credit are not the same thing.
A deduction reduces taxable income.
A credit generally reduces the amount of tax owed after the tax calculation.
For example, if you qualify for a $10,000 deduction, you do not automatically receive $10,000 back as a refund.
If your marginal tax rate is 22%, a simplified illustration would be:
$10,000 × 22% = $2,200
That does not mean every taxpayer will save exactly $2,200.
The actual tax benefit depends on the taxpayer’s income, tax brackets, other deductions, credits, and individual circumstances.
This is one reason headlines promising that a tax deduction will “save you $10,000” can be misleading.
The deduction reduces taxable income; it does not generally provide a dollar-for-dollar tax refund.
Marginal Tax Rate vs. Effective Tax Rate
Understanding tax brackets is also important when evaluating deductions.
Federal income tax uses marginal brackets.
For 2026, the federal rates remain:
10%
12%
22%
24%
32%
35%
37%
Being in the 22% tax bracket does not mean your entire taxable income is taxed at 22%.
Only the portion of taxable income falling within that bracket is taxed at 22%.
Your effective tax rate is the average percentage of taxable income that actually goes toward federal income tax.
This distinction matters because the value of a deduction depends partly on where the deduction reduces taxable income.
A $5,000 deduction does not necessarily mean your federal tax bill falls by $5,000.
Choosing Between the Standard Deduction and Itemizing
Many taxpayers have to decide whether to take the standard deduction or itemize.
The standard deduction is simple.
Itemizing can potentially provide a larger deduction when a taxpayer has enough qualifying expenses.
Common itemized deductions can include certain:
Medical and dental expenses
State and local taxes
Mortgage interest
Charitable contributions
Casualty losses
However, the rules and limitations can be complicated.
The higher SALT limit in 2026 may make itemizing more attractive for some taxpayers, particularly those with substantial state and local taxes.
The new non-itemizer charitable deduction, on the other hand, gives certain taxpayers who use the standard deduction a separate benefit for qualifying cash donations.
This means taxpayers should compare both methods rather than assuming that one method is always better.
Tax Planning Tips for 2026
Do not wait until filing season to organize your records.
If you expect to claim any of the deductions discussed above, keep documentation throughout the year.
For employees, this can include:
W-2 forms
Pay stubs
Overtime records
Tip records
Auto-loan statements
For homeowners and taxpayers who itemize, this can include:
Property tax records
State tax records
Mortgage-interest statements
Charitable receipts
Medical expense records
Disaster-loss documentation
For business owners:
Business income records
Business expense records
Payroll records
QBI-related information
Retirement contribution records
You should also pay attention to your modified adjusted gross income because several of the new deductions phase out at higher income levels.
A taxpayer who qualifies for a deduction at one income level may receive a smaller deduction after income increases.
Important 2026 Tax Filing Mistakes to Avoid
Mistake 1: Confusing Tax Year 2026 With the 2026 Filing Season
Tax year 2026 generally refers to income earned during 2026 and a return filed in 2027.
The 2026 filing season primarily concerns 2025 tax returns.
Mistake 2: Assuming Every Tip Is Deductible
Only qualifying tips under the applicable rules count toward the tip deduction.
Mistake 3: Treating All Overtime Pay as Deductible
The overtime deduction generally focuses on the qualified overtime portion rather than every dollar of overtime wages.
Mistake 4: Assuming Every Car Loan Qualifies
The vehicle and loan must satisfy specific requirements.
Lease payments do not qualify for the car-loan-interest deduction.
Mistake 5: Ignoring Income Phaseouts
Several new deductions begin to phase out above specified MAGI thresholds.
Mistake 6: Confusing Deductions With Credits
A $10,000 deduction is not the same as a $10,000 tax credit.
Mistake 7: Forgetting Documentation
Tax deductions generally need supporting records.
Do not wait until the last minute to reconstruct receipts, statements, or other documentation.
Mistake 8: Assuming a State Tax Rule Is the Same as a Federal Rule
A federal deduction may have different state tax consequences.
Always check the rules for the state where you file.
2026 Tax Deduction Checklist
Before filing or preparing for your 2026 return, review whether any of these provisions apply to you:
Standard deduction
Additional senior standard deduction
Enhanced $6,000 senior deduction
Qualified tips deduction
Qualified overtime deduction
Qualified car-loan-interest deduction
Higher SALT deduction limit
Charitable deduction for qualifying non-itemizers
Qualified Business Income deduction
Casualty losses from qualifying state- or federally declared disasters
Also review:
Your filing status
Your modified adjusted gross income
Your age
Your retirement contributions
Your business income
Your charitable contributions
Your mortgage interest
Your state and local taxes
Your qualifying vehicle loan interest
Your tip and overtime records
Your disaster-loss documentation
Frequently Asked Questions
What is the 2026 standard deduction?
For tax year 2026, the standard deduction is $16,100 for single filers and married individuals filing separately, $32,200 for married couples filing jointly, and $24,150 for heads of household.
What is the new $6,000 senior deduction?
Eligible taxpayers age 65 or older may claim an additional deduction of up to $6,000 for tax years 2025 through 2028. A married couple filing jointly may potentially claim up to $12,000 if both spouses qualify. Income phaseouts apply.
Can tipped workers deduct tips in 2026?
Eligible workers may be able to deduct up to $25,000 of qualified tips, subject to occupation, reporting, income, and other requirements.
How much overtime can be deducted in 2026?
Eligible taxpayers may deduct up to $12,500 of qualified overtime compensation. The limit is $25,000 for married couples filing jointly, subject to the applicable rules and income phaseouts.
Is car loan interest deductible in 2026?
Eligible taxpayers may deduct up to $10,000 of interest paid on qualifying passenger vehicle loans, subject to vehicle, loan, income, and other requirements. Lease payments do not qualify.
What is the 2026 SALT deduction limit?
The 2026 SALT limit is $40,400 for most taxpayers and $20,200 for married taxpayers filing separately. Higher-income taxpayers can face a phaseout.
Can I deduct charitable donations if I take the standard deduction?
Beginning with tax year 2026, eligible non-itemizers may deduct up to $1,000 of qualifying cash charitable contributions, or $2,000 for married couples filing jointly, subject to the applicable requirements.
Is the QBI deduction still available in 2026?
Yes. The Qualified Business Income deduction was made permanent, and additional 2026 rules apply to eligible businesses.
Can state-declared disaster losses qualify for a federal deduction in 2026?
Beginning with tax year 2026, qualifying personal casualty losses associated with state-declared disasters can qualify, subject to the applicable requirements and limitations.
When will I file my 2026 tax return?
Tax year 2026 generally covers income earned during 2026, and the federal income tax return for that year will generally be filed in 2027.
Final Thoughts
The 2026 tax year includes several important deductions and tax changes that taxpayers should understand before filing.
The standard deduction is higher, seniors may qualify for an additional $6,000 deduction, eligible tipped workers can potentially deduct qualified tips, and qualifying overtime compensation can receive a new deduction.
Taxpayers may also be able to deduct qualifying car-loan interest, while the SALT deduction limit is substantially higher than under the previous limit.
Another important change is the new charitable deduction available to certain taxpayers who take the standard deduction.
Small-business owners should also review the permanent Qualified Business Income deduction, while taxpayers affected by qualifying disasters should understand the expanded casualty-loss rules.
But tax planning is not simply about finding the biggest number.
A deduction only helps if you actually qualify for it.
Income limits, filing status, age, type of income, documentation, phaseouts, and other requirements can all affect the final result.
It is also important to distinguish between tax year 2026 and the 2026 filing season. Some provisions first applied to 2025 income and are already relevant to returns filed in 2026, while other changes apply specifically to income earned during 2026 and will generally affect returns filed in 2027.
Before filing, review the latest IRS instructions and make sure your records support every deduction you claim.
The goal is not to claim every tax break you hear about online.
The goal is to identify the deductions that genuinely apply to your situation, understand their limitations, and report them accurately.